Table of Content
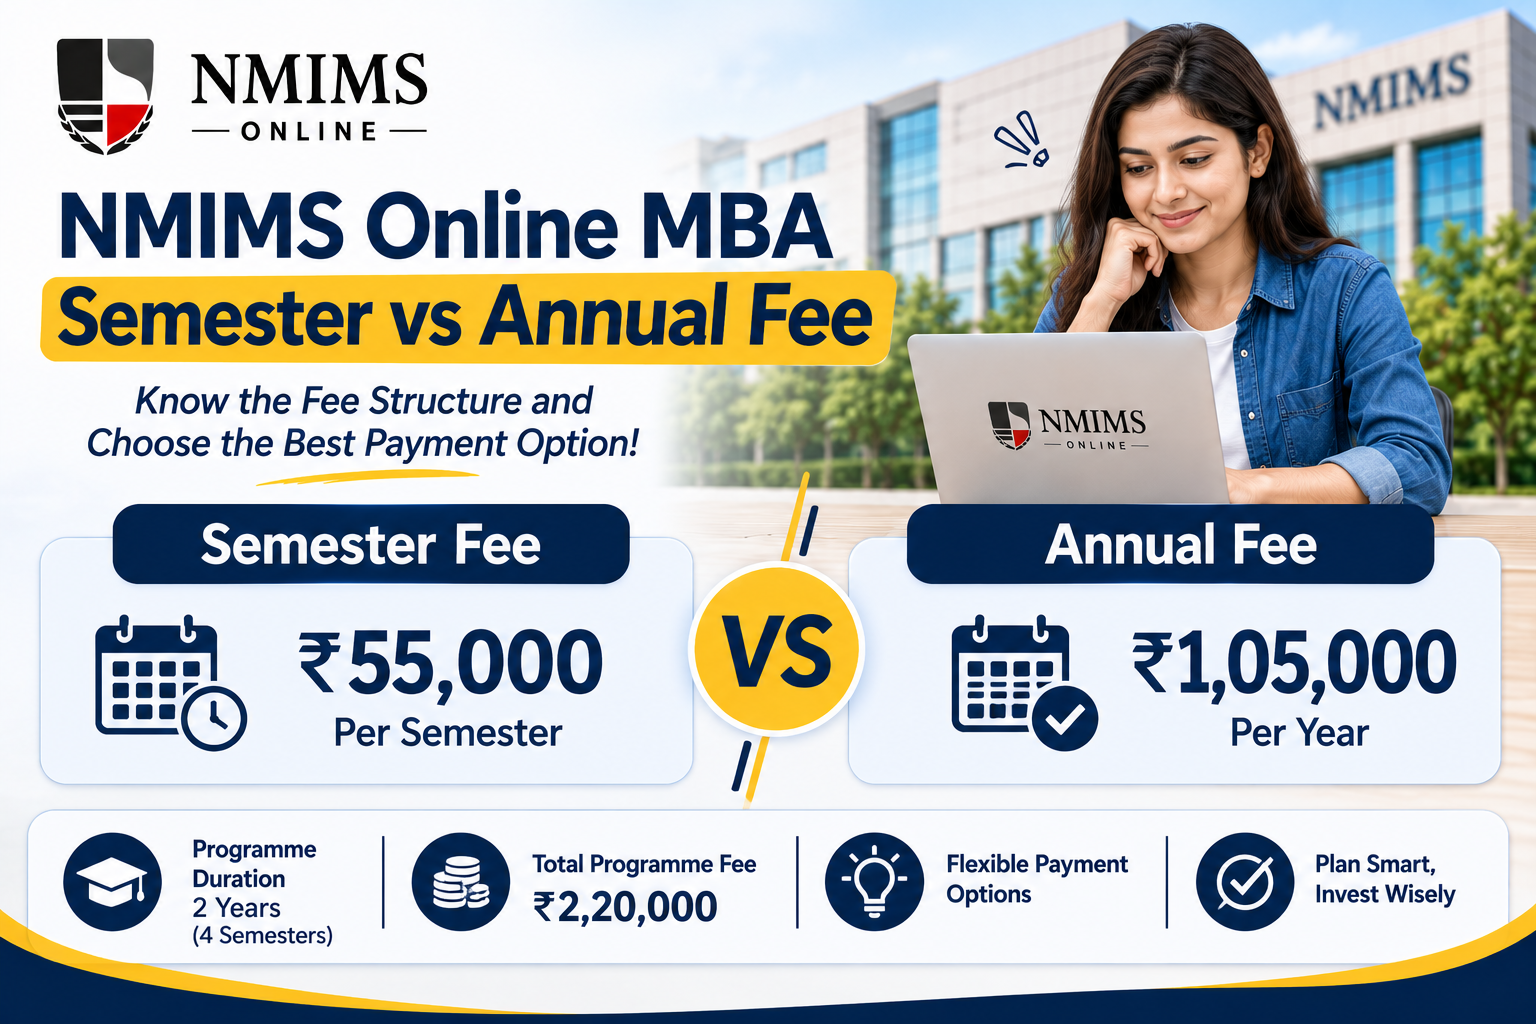
The NMIMS Online MBA semester fee is ₹55,000 for each of four semesters, creating a nominal programme-fee total of ₹2,20,000. The annual route is ₹1,05,000 per year for two years, or ₹2,10,000 nominally. Annual payment therefore costs ₹10,000 less than semester payment under the fee table.
NMIMS also lists a ₹1,96,000 full programme-fee option. That is nominally ₹14,000 below the annual route and ₹24,000 below the semester route. Separate processing, examination, project, late-admission and finance costs still need to be budgeted.
NMIMS Online MBA Payment Options at a Glance
| Route | Published payment | Scheduled payments | Nominal programme-fee total | Main trade-off |
|---|---|---|---|---|
| Full programme fee | ₹1,96,000 | 1 | ₹1,96,000 | Lowest nominal total; highest immediate outflow |
| Annual payment | ₹1,05,000 per year | 2 | ₹2,10,000 | Middle total; two larger payment events |
| Semester payment | ₹55,000 per semester | 4 | ₹2,20,000 | Smaller scheduled instalment; highest nominal total |
Direct Answer: Which Route Costs Less?
If only the currently published programme-fee amounts are compared, full payment costs the least, annual payment comes next and semester-wise payment has the highest nominal total.
| Comparison | Arithmetic difference |
|---|---|
| Full payment vs annual total | Full payment is ₹14,000 lower |
| Full payment vs semester total | Full payment is ₹24,000 lower |
| Annual total vs semester total | Annual payment is ₹10,000 lower |
However, the lowest university-fee total is not automatically the lowest personal cost. Borrowing to make a full payment may add interest and charges. Using all available savings may weaken an emergency fund. Missing a later instalment can also create academic or administrative problems.
Start Your Journey
Need Help Picking the Right Fee Route?
Talk to our admissions team about tuition options, complete cost and how each route affects your cash flow.
What the ₹10,000 Initial Amount Means
The ₹10,000 from the programme fee is collected at registration. It is not described as a fourth payment route or an extra tuition charge.
Before completing the next payment, confirm:
- How the ₹10,000 is adjusted against the selected route.
- What balance is due after registration.
- When the next scheduled payment becomes payable.
- Whether a route can be changed after the initial amount is paid.
- Whether any adjustment depends on document approval.
The ₹1,200 admission-processing fee is separately listed. Keep the receipt or portal breakdown showing both components.
Full Programme Payment: Benefits and Risks
Why someone may choose it
- It has the lowest nominal programme-fee total in the current table.
- It removes the need to plan multiple programme-fee due dates.
- It avoids external borrowing only when the applicant already has the funds.
- The difference from annual and semester totals is easy to calculate.
What to evaluate first
- Will the payment reduce emergency savings below a comfortable level?
- Is any part of the amount coming from a credit card or high-cost loan?
- Have you read the current cancellation and refund policy?
- Are eligibility and documents sufficiently clear before the large payment?
- Does the payment receipt show the full programme route correctly?
The nominal ₹14,000 difference from annual payment is a useful break-even reference. If interest, lender processing or other costs incurred solely to make the full payment exceed the benefit, it may no longer be the cheaper personal choice.
Annual Payment: Benefits and Risks
The annual route publishes ₹1,05,000 per year. Across two years, the nominal programme-fee total is ₹2,10,000.
Why someone may choose it
- It requires less cash initially than full payment.
- It is nominally ₹10,000 lower than the four-semester route.
- It creates only two major programme-fee payment events.
- It may allow the second-year amount to be built from future income.
What to evaluate first
- Can you reserve the second annual payment before it is due?
- Will variable income make the second payment difficult?
- What happens if employment or household cash flow changes?
- Are due-date reminders and a separate savings plan in place?
- Will the fee schedule remain the same for the learner after enrolment, and where is that stated?
Semester-Wise Payment: Benefits and Risks
The semester route publishes ₹55,000 per semester for four semesters. Its nominal programme-fee total is ₹2,20,000.
Why someone may choose it
- Each scheduled programme-fee instalment is smaller than an annual payment.
- It may match salary-based budgeting more comfortably.
- It reduces the amount committed at one time.
- It may avoid borrowing for a larger annual or full payment.
What to evaluate first
- The current nominal total is ₹10,000 above annual payment.
- Four due dates require more active planning.
- Examination and project charges can arise separately from the semester fee.
- A missed payment can affect academic access or continuation under current rules.
- A smaller instalment should not be mistaken for a lower total cost.
Semester payment can be financially sensible when it avoids expensive borrowing or protects essential savings, even though its nominal university-fee total is higher.
Cash-Flow Planning Examples
Example 1: Building the next annual payment
If a learner wants to accumulate ₹1,05,000 over 12 months, the simple monthly saving target is:
₹1,05,000 ÷ 12 = ₹8,750 per month
If the actual due date is earlier, the required monthly amount increases. Always replace the 12-month assumption with the real interval shown in the student schedule.
Example 2: Building the next semester payment
If ₹55,000 needs to be accumulated over six months, the simple monthly target is:
₹55,000 ÷ 6 = approximately ₹9,167 per month
Again, six months is an illustration. The real semester payment date controls the plan.
Example 3: Comparing full payment with a loan
Suppose a learner needs external finance only to choose the ₹1,96,000 route. Compare:
Lender interest + lender fees + related costs against the ₹14,000 nominal gap from annual payment.
If the external cost is higher than the gap, self-funded annual payment may cost less overall. This is a comparison method, not a recommendation to borrow or a prediction of a lender’s terms.
Costs That Do Not Disappear with the Payment Route
Choosing full, annual or semester payment changes the programme-fee schedule. It does not automatically remove separately applicable charges.
| Separate item | Current published basis | Why totals vary |
|---|---|---|
| Admission-processing fee | ₹1,200 | Paid at admission; separately listed |
| Examination fee | ₹800 per subject per attempt | Depends on charged subjects and attempts |
| Project fee | ₹800 per attempt | Another attempt can add cost |
| Late-admission fee | ₹500 or ₹1,000 in current bands | Depends on application date |
| Loan or EMI cost | Lender’s agreement | Depends on interest, fees and repayment terms |
A Five-Step Decision Framework
Step 1: Calculate the same total for every route
Start with ₹1,96,000, ₹2,10,000 and ₹2,20,000 as the current nominal programme-fee totals. Add the same reasonable estimate for processing, assessments and project attempts.
Step 2: Protect essential liquidity
Subtract the payment from available funds. Check whether rent, household costs, insurance, debt obligations and emergency reserves remain covered.
Step 3: Add the complete finance cost
If borrowing is required, use the total repayable amount, not the advertised EMI. Include interest, processing, documentation, insurance, taxes, penalties and foreclosure terms where applicable.
Step 4: Test the next due date
For annual and semester routes, plan how the next payment will be accumulated. Use conservative income assumptions, not a hoped-for promotion or salary increase.
Step 5: Read cancellation and change terms
Understand the current refund schedule, non-refundable amounts, loan-provider responsibilities and how the university communicates fee changes.
Which Route May Fit Different Situations?
| Situation | Route worth evaluating | Main condition to check |
|---|---|---|
| Full amount available after protecting emergency savings | Full payment | Refund terms and opportunity cost |
| Two larger payments fit predictable income | Annual payment | Ability to reserve the second-year amount |
| Smaller instalments reduce borrowing need | Semester payment | Higher nominal total and four due dates |
| Full payment requires expensive debt | Annual or semester | Compare total finance cost, not EMI |
| Income is irregular | Route with safer cash buffer | Build reserve before the due date |
Conclusion
Annual NMIMS Online MBA payment costs ₹10,000 less than semester-wise payment under the schedule checked on 21 August 2026. Full payment has the lowest nominal programme-fee total. Choose only after comparing liquidity, next due dates, separate academic charges, refund exposure and any lender’s complete cost. A smaller instalment is easier to pay now, but it is not automatically cheaper overall.
Frequently Asked Questions
Annual payment is cheaper under the current nominal programme-fee table. Two annual payments total ₹2,10,000, while four semester payments total ₹2,20,000, a difference of ₹10,000.